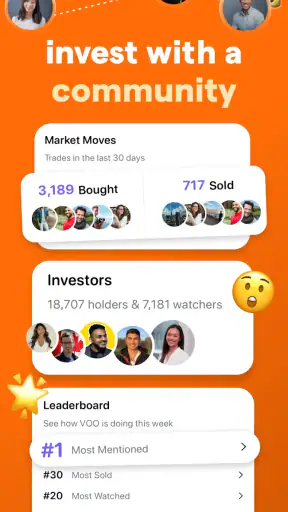
I approached Blossom: Social Investing as a finance app first and a social investing tool second. That distinction matters. An app that lets me watch stocks, ETFs, dividends, and other investors’ portfolios can be useful for learning and organizing ideas, but it also sits close to decisions that affect real money. My experience was most positive when I treated it as a research and observation space rather than as a shortcut to confident investment choices.
Blossom Social Inc. has built something aimed at people who want more context than a bare price chart provides. Instead of only checking whether an asset went up or down, I can use the app to look at income-oriented ideas, compare portfolio approaches, and follow how other investors structure their holdings. That social layer gives the app a different feel from a traditional brokerage account, while the finance category makes its limits especially important to understand.
What trust looks like when an investing app is social
The app is free to install, with optional in-app purchases ranging from $6.49 to $119.99 per item. That combination makes the first step easy, but it also means I would pay attention to which parts of the experience are available without spending and which tools are placed behind a purchase. A free starting point is helpful for exploring the interface before deciding whether the extra cost fits my needs.
Blossom has an average rating of 4.5 from around 4.4 thousand ratings, and it has passed 100 thousand installs. Those figures suggest that the app has attracted a meaningful audience, but they do not replace my own checks. A finance app deserves a slower evaluation than a casual entertainment download because the consequences of misunderstanding a screen, a portfolio, or an investing idea can be much larger.
The app was released on August 3, 2022, and the current version is 3.7.8. It is rated for Teen users and works on Android 6.0 or later. I see the age label as a reminder that younger users may encounter investing concepts before they have much experience with risk, taxes, or long-term planning. The interface may be approachable, but approachable does not mean that every idea shown inside it is suitable for every person.
What I like about the social format is that it can expose me to questions I might not ask while looking at a standard market list. Why does someone favor dividend-paying companies? How concentrated is an income-focused portfolio? Is an attractive yield connected to a business with weaker growth or greater uncertainty? Those are useful questions, and the app can make them feel more concrete by placing investment ideas in a portfolio context.
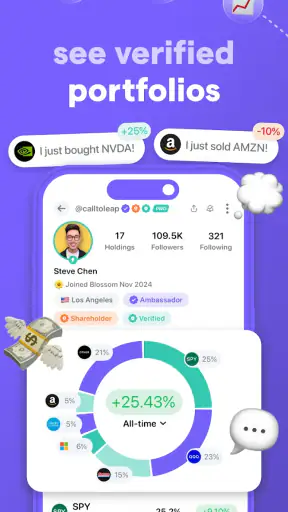
At the same time, social visibility can create a false sense of reassurance. Seeing another person hold an asset does not tell me whether that asset suits my goals, time horizon, tax situation, or tolerance for losses. A portfolio can look sensible while still being unsuitable for my circumstances. I would therefore use the social feed as a source of ideas and contrasting viewpoints, not as a ranking of people to copy.
Why the portfolio view is more useful than a simple watchlist
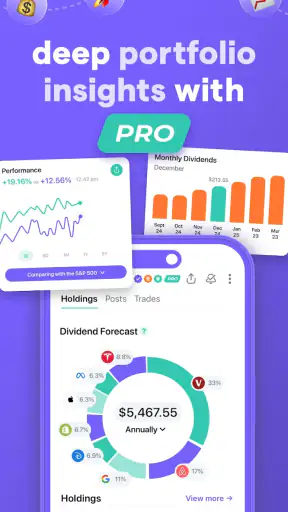
A conventional watchlist answers a narrow question: which assets am I monitoring? Blossom’s emphasis on investor portfolios encourages a broader review. I can think about combinations rather than isolated tickers, and that changes the quality of the research. An ETF that looks appealing alone may overlap heavily with several companies already present in a portfolio. A high-dividend holding may also increase exposure to one industry. Looking at groups of holdings helps reveal those trade-offs earlier.
My practical suggestion is to create a small note outside the app while browsing. For each portfolio or idea that catches my attention, I would record the reason it interests me, the risk I can already see, and the question I still need to answer. This prevents the social feed from turning into an endless stream of attractive-looking ideas. It also gives me a way to distinguish a genuine research lead from a momentary reaction to a popular holding.
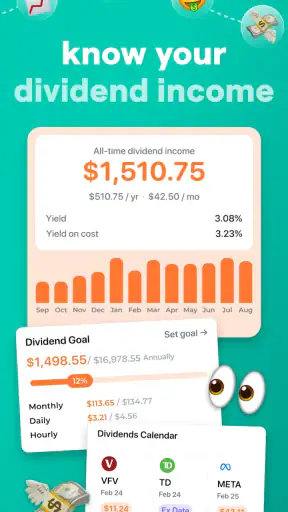
Another useful habit is to separate income from total return in my thinking. Dividends can feel tangible because they are paid out, but they are not automatically a sign of safety or superior performance. When I explore dividend-focused portfolios, I would look beyond the payment itself and ask how diversified the holdings are, whether the income appears dependent on a narrow group of companies, and whether the strategy matches my need for cash now versus growth later.
Controls I would check before becoming a regular user
Trust is not only about whether an app looks polished. It is also about whether I can understand what I am viewing, decide what I want to follow, and leave without feeling pushed into a commitment. In Blossom, the most important controls for me are the choices around following portfolios, reviewing assets, and deciding whether optional purchases are worthwhile. I would explore those areas calmly rather than accepting every prompt during the first session.
I would also review account-related screens before adding more personal information than necessary. A social investing app may be useful simply as a research companion, so I would ask myself whether a requested detail is needed for the feature I actually want. If my goal is to study portfolios and dividends, I would avoid treating the app like a brokerage unless I specifically needed a function that requires a deeper account relationship.
That distinction is one of the app’s strongest practical advantages: it can fit into a research workflow without replacing the brokerage or financial planning tools I already use. I can examine ideas here, then verify them through primary company information, fund documents, and my own investment account. Keeping those jobs separate reduces the chance that an attractive social presentation becomes an immediate transaction.
When I use any finance app, I prefer visible choices over automatic behavior. I want to know what I am following, what appears in my feed, and which actions require confirmation. If the app offers an account-control screen, I would make a point of checking notification preferences, followed content, and any saved information before settling into daily use. Those small checks are easy to skip, but they determine whether the app feels like a tool I control or a feed that controls my attention.
Where data sensitivity matters most
The most sensitive moment is not necessarily the first time I browse a stock. It is the point where browsing turns into personal finance. A portfolio can reveal interests, habits, and risk preferences even when it does not show a complete financial picture. I would be careful about treating social activity as harmless, especially if I am sharing details that make my investing behavior easy to identify.
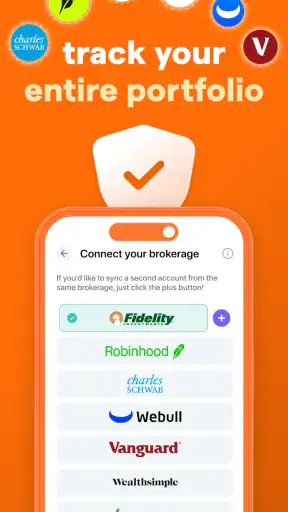
I would also pause before connecting any financial account or entering information that is not essential to my purpose. The right decision depends on the exact screen and the choices presented there, so I would read those prompts rather than tapping through them automatically. My rule is simple: if I cannot explain why the app needs a piece of information, I do not provide it until I understand the reason.
Notifications deserve similar attention. Market alerts and social updates can be helpful, but frequent prompts may encourage reactive decisions. I prefer notifications that support a planned review, such as checking a portfolio at a chosen time, rather than interruptions that make every price move feel urgent. If the available controls let me reduce the noise, I would do that early.
There is also a privacy trade-off in following real investor portfolios. The feature is valuable precisely because it gives investing behavior a social context, yet that context can tempt users to share more than they intended or to interpret public activity as a complete financial profile. I would keep my own profile conservative and avoid assuming that another person’s visible portfolio represents all of their assets, liabilities, or goals.
For families, the Teen content rating is worth considering alongside supervision and financial education. I would not hand the app to a younger user as a substitute for a conversation about risk. Instead, I would use it, if appropriate, to discuss diversification, dividends, and the difference between researching an investment and buying one. The social element makes those conversations easier to illustrate, but it can also make imitation feel more natural than independent thinking.
How I would use it in an ordinary week
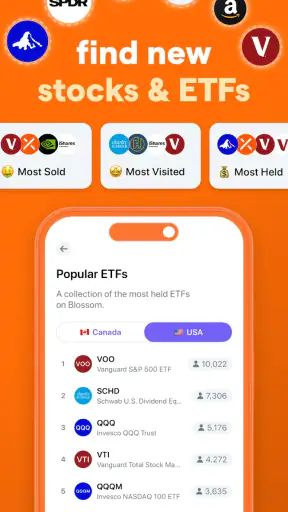
Imagine I am reviewing my finances on a Sunday afternoon. I want to understand whether my portfolio is too concentrated in income-producing assets, but I do not want to trade immediately. I would open Blossom, look through dividend and ETF ideas, and compare several investor portfolios for patterns. I might notice that different people reach similar income goals with very different mixes of funds and individual companies.
Instead of copying the most appealing portfolio, I would write down the recurring themes: concentration, sector exposure, the balance between funds and individual shares, and whether the portfolio appears designed for current income or long-term growth. I would then verify those themes elsewhere before making any decision. The app’s value in this scenario is not that it tells me what to buy. It helps me form better questions.
A second use case is learning. Someone new to investing may understand a company more easily when it appears alongside other holdings and a stated strategy. I would use that context to build a vocabulary around diversification and portfolio construction. However, I would keep a beginner’s expectations realistic: social portfolios can simplify complex decisions, and a clean presentation cannot show every risk that matters.
For an experienced investor, the app may work better as a discovery layer than as a complete analytical workstation. It can help surface portfolios, dividend themes, and ETF comparisons, while a dedicated brokerage, spreadsheet, or research platform may remain better for execution, tax records, detailed valuation work, and long-term performance analysis. That division of labor feels sensible to me rather than a weakness unique to Blossom.
Where it fits beside familiar alternatives
Compared with a brokerage app, Blossom is more naturally suited to observation and social discovery than to placing trades or managing the full administrative side of investing. A brokerage is usually the better destination when I need execution, holdings administration, or account-specific records. Blossom is more interesting when I want to see how ideas are assembled and learn from contrasting portfolio choices.
Compared with a plain stock tracker, it offers a more human angle. A tracker can be cleaner for checking prices and personal performance, while Blossom’s portfolio focus gives me more context around why an asset might appear in a strategy. The trade-off is that social context can add noise. If I only want a quiet list of prices, alerts, and charts, a conventional tracker may be less distracting.
Compared with a discussion forum, the finance focus is an advantage because portfolios, ETFs, and dividends give conversations a clearer subject. Still, I would not treat any social investing space as a substitute for professional advice or primary research. The best use is selective: follow ideas, challenge my assumptions, and verify before acting.
The optional purchase model is another reason to compare carefully. Since the app is free to start but includes purchases that can reach $119.99 per item, I would test the free experience against my actual routine before paying. A premium feature is worthwhile only if it saves me meaningful time or improves a decision process I already understand. Paying to access more information does not automatically make that information more reliable.
Small habits that make the experience safer
- Use social portfolios as research prompts. When a holding interests me, I would investigate the asset itself instead of treating another investor’s choice as an endorsement.
- Review combinations, not just individual yields. Several attractive income holdings can still create concentration or overlapping exposure.
- Separate browsing from buying. I would give every idea a cooling-off period and verify it through sources outside the app.
- Keep sharing deliberate. I would inspect profile and notification choices so that the social layer supports my goals instead of exposing more activity than I intended.
- Test before paying. I would use the free entry point long enough to identify a specific problem that an optional purchase would solve.
These habits also answer an important question: can I use the app without becoming an active trader? Yes, and that is how I think it works best. I can browse portfolios, study dividend approaches, and organize research without turning every discovery into a transaction. For me, that slower approach protects the educational value of the app.
Who should choose it, and who should skip it
I would recommend Blossom to a curious investor who learns well by comparing real portfolio structures. It is especially appealing if I want to explore ETFs, dividend strategies, and the reasoning implied by different collections of holdings. It can also help someone who finds a standard ticker list too abstract and wants a more visual, people-centered way to begin asking investment questions.
I would be more cautious recommending it to someone looking for direct, personalized financial guidance. Following another investor is not the same as receiving advice tailored to my income, debts, goals, or risk capacity. I would also point frequent traders toward a dedicated trading platform if execution speed, advanced order handling, or account management is the main priority.
Someone who dislikes social feeds may find the central concept distracting. The same feature that adds context for one user can create comparison pressure for another. If I know that seeing other portfolios makes me chase performance or change plans impulsively, I would either use the app sparingly or choose a quieter research tool.
Finally, I would skip optional spending until I can name a clear benefit. The free starting point lowers the barrier to testing the app, but the presence of paid items means I should not confuse a larger feature set with a better investing process. My decisions should remain grounded in my plan, not in the number of tools available on screen.
A cautious verdict on Blossom
Blossom: Social Investing is most convincing as a bridge between a basic market tracker and a full brokerage account. Its focus on stocks, ETFs, dividends, and investor portfolios gives me a practical way to study how ideas fit together. The social angle is genuinely useful when I use it to compare approaches and uncover questions that a price list would never raise.
Its main risk is behavioral rather than technical: social proof can make an investment look safer or more suitable than it really is. I would protect myself by treating every portfolio as a case study, checking account and privacy choices carefully, limiting notifications, and verifying important information elsewhere. Those steps preserve the app’s educational value without handing over my judgment.
After using it in that way, I see a free finance app from Blossom Social Inc. that is worth trying for thoughtful learners, particularly those interested in income strategies and portfolio construction. I would not use it as my only research source, my financial adviser, or my primary account manager. The best reason to install it is to improve the questions I ask before investing, not to outsource the answers.


